
Women are becoming one of the fastest-growing sources of wealth accumulation in the world, and wealth management firms are still catching up to what that actually means. Rising income, greater financial independence, and a much more active role in household financial decisions are all pushing this shift forward at once. Two things are really driving it, an enormous transfer of existing wealth toward women and their growing role as wealth creators and investors in their own right, not just recipients of someone else’s estate plan.
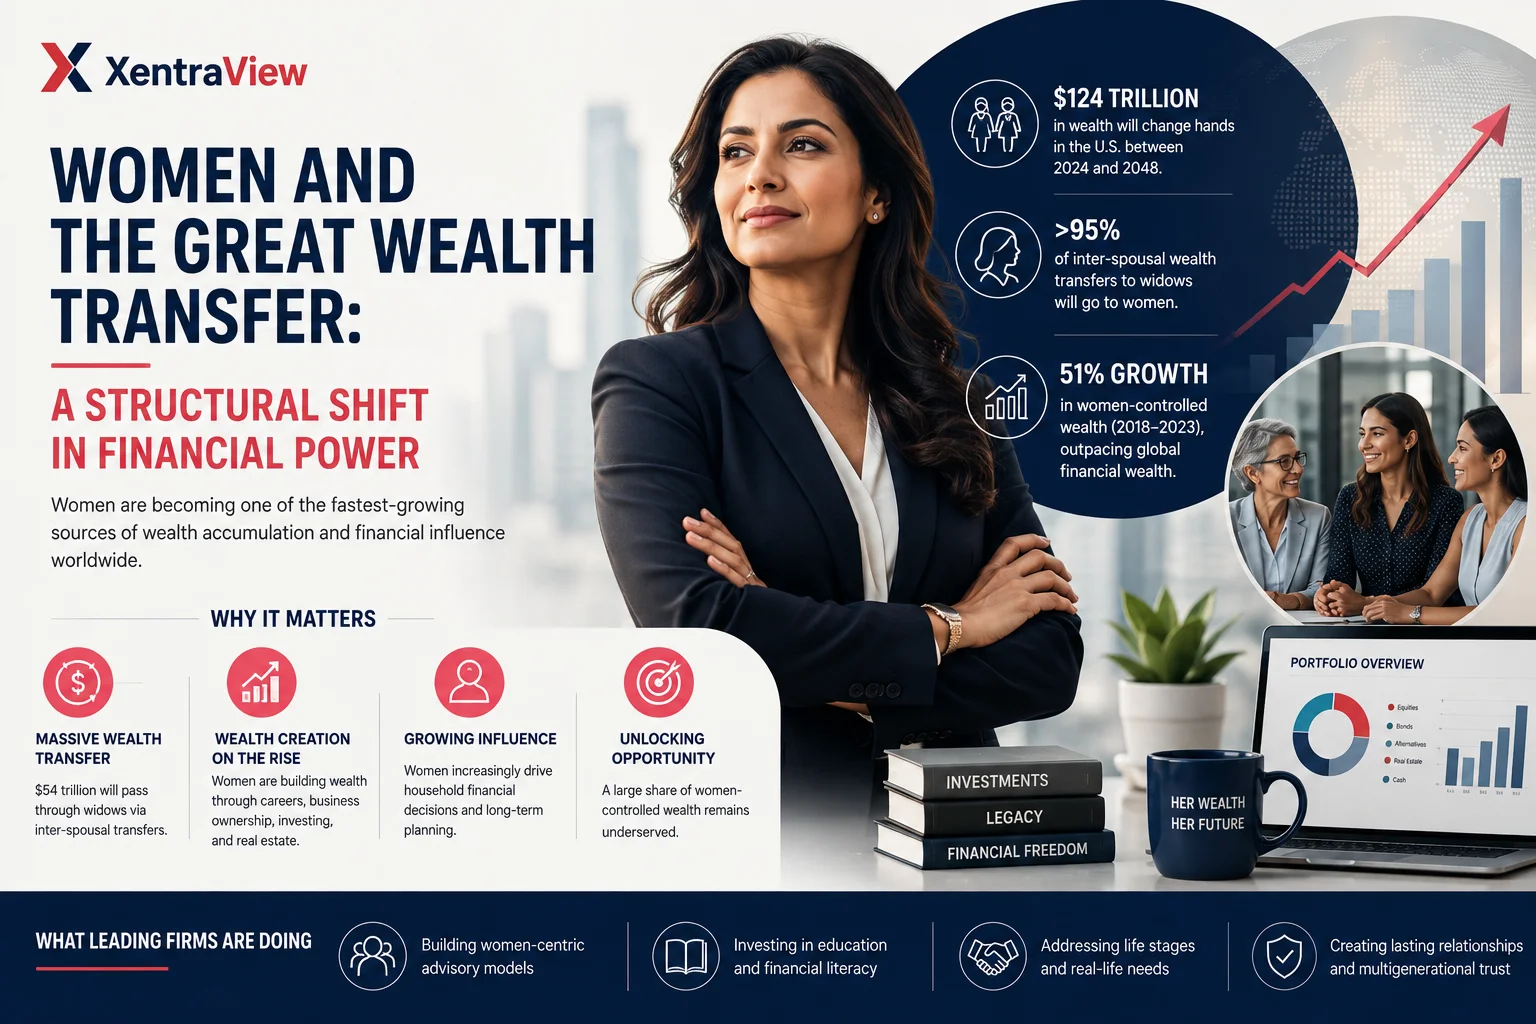
The scale of the transfer sitting at the center of this is genuinely hard to grasp. Cerulli Associates projects $124 trillion in wealth will change hands in the US between 2024 and 2048, and a meaningful chunk of that will move through spouses before it ever reaches the next generation. Of that total, $54 trillion is expected to pass through inter-spousal transfers to widows, and more than 95% of that money is going to women, mostly because women statistically outlive their husbands. That puts women in the position of managing an outsized share of this transition, whether they feel ready for it or not.
 Why This Is a Structural Shift, Not a Cycle
 Why This Is a Structural Shift, Not a Cycle
It’s tempting to file the Great Wealth Transfer under “generational handover” and move on. That undersells what’s actually happening. This is a genuine structural change in who controls capital and who makes the decisions about where it goes, and the effects will play out over decades, not one news cycle.
The AUM numbers already show it. McKinsey found that wealth controlled by women grew 51% between 2018 and 2023, well ahead of the 43% growth seen in global financial wealth overall during the same stretch. That gap is the whole story in one number: female-controlled wealth isn’t just riding the broader market up; it’s genuinely outpacing it. The trend is especially visible in the US and Europe, where women’s share of retail financial assets is already climbing toward the 40% to 45% range projected for 2030.
Here’s the uncomfortable part, though. Control is growing faster than preparedness. HSBC Research, published in March, found that women are expected to control more than 40% of global wealth by 2030, and yet a lot of affluent women still say they feel genuinely unprepared for aging, caregiving, and long-term planning decisions. That gap between how much wealth women control and how supported they feel managing it is exactly where firms either win real loyalty or lose it. The ones that close that gap with relevant content, better-trained advisors, and planning frameworks that actually map to real life stages are the ones positioned to hold onto this growing asset base.
It’s Not Just About Inheritance
The transfer piece gets most of the headlines, but a lot of this wealth is being built from scratch, not just handed down. Millennial women in particular are accumulating wealth through careers, entrepreneurship, real estate, and genuinely active investing, which widens the whole opportunity well beyond inherited assets.
Investing remains the foundation for most of this, but younger women are layering it with business ownership, executive roles, and real estate in a way older generations didn’t as much. There’s real experimentation happening too, women are moving beyond traditional portfolios into alternatives, private markets, and their own entrepreneurial bets, without abandoning core investing as the base of it all. RBC Wealth Management’s 2026 US high-net-worth survey found that 62% of Millennial women point to business ownership and innovation as a driver of their wealth, and 43% point to executive roles, both numbers running well ahead of what Gen X and Boomer women report.
Why This Actually Matters for Wealth Managers
A few things make this more than a marketing angle.
There’s a real asset growth and retention story here. Women are gaining control of substantial assets through both earned wealth and transfer, and firms that manage to retain spouses and next-generation clients through that transition are sitting on a genuinely durable opportunity, not a one-time windfall.
The advice model itself needs to stretch further than it currently does. Women’s financial needs often touch longevity, caregiving, divorce, widowhood, entrepreneurship, retirement, and legacy planning all at once, which is a lot more holistic than the standard portfolio-review conversation most advisory models were built around.
And there’s real unmanaged upside sitting on the table. A large share of women-controlled assets remains underserved or entirely unmanaged today, which is a sizeable opportunity for firms willing to deliver genuinely relevant advice and build stronger relationships instead of treating this as a niche segment to check a box on.
Where Leading Firms Are Actually Headed
The firms taking this seriously are building specialized offerings, real education initiatives, and advisory models tailored to how women’s financial lives actually unfold, rather than retrofitting a generic model with different marketing. That distinction matters. Women don’t need a pink version of the same advisory experience. They need advisors and firms that understand the specific decisions, caregiving, widowhood, business ownership, and legacy planning that are actually going to define how this wealth gets managed over the next two decades.
The firms that get ahead of this now, before the bulk of the transfer even happens, are the ones likely to be trusted with it when it does.
