
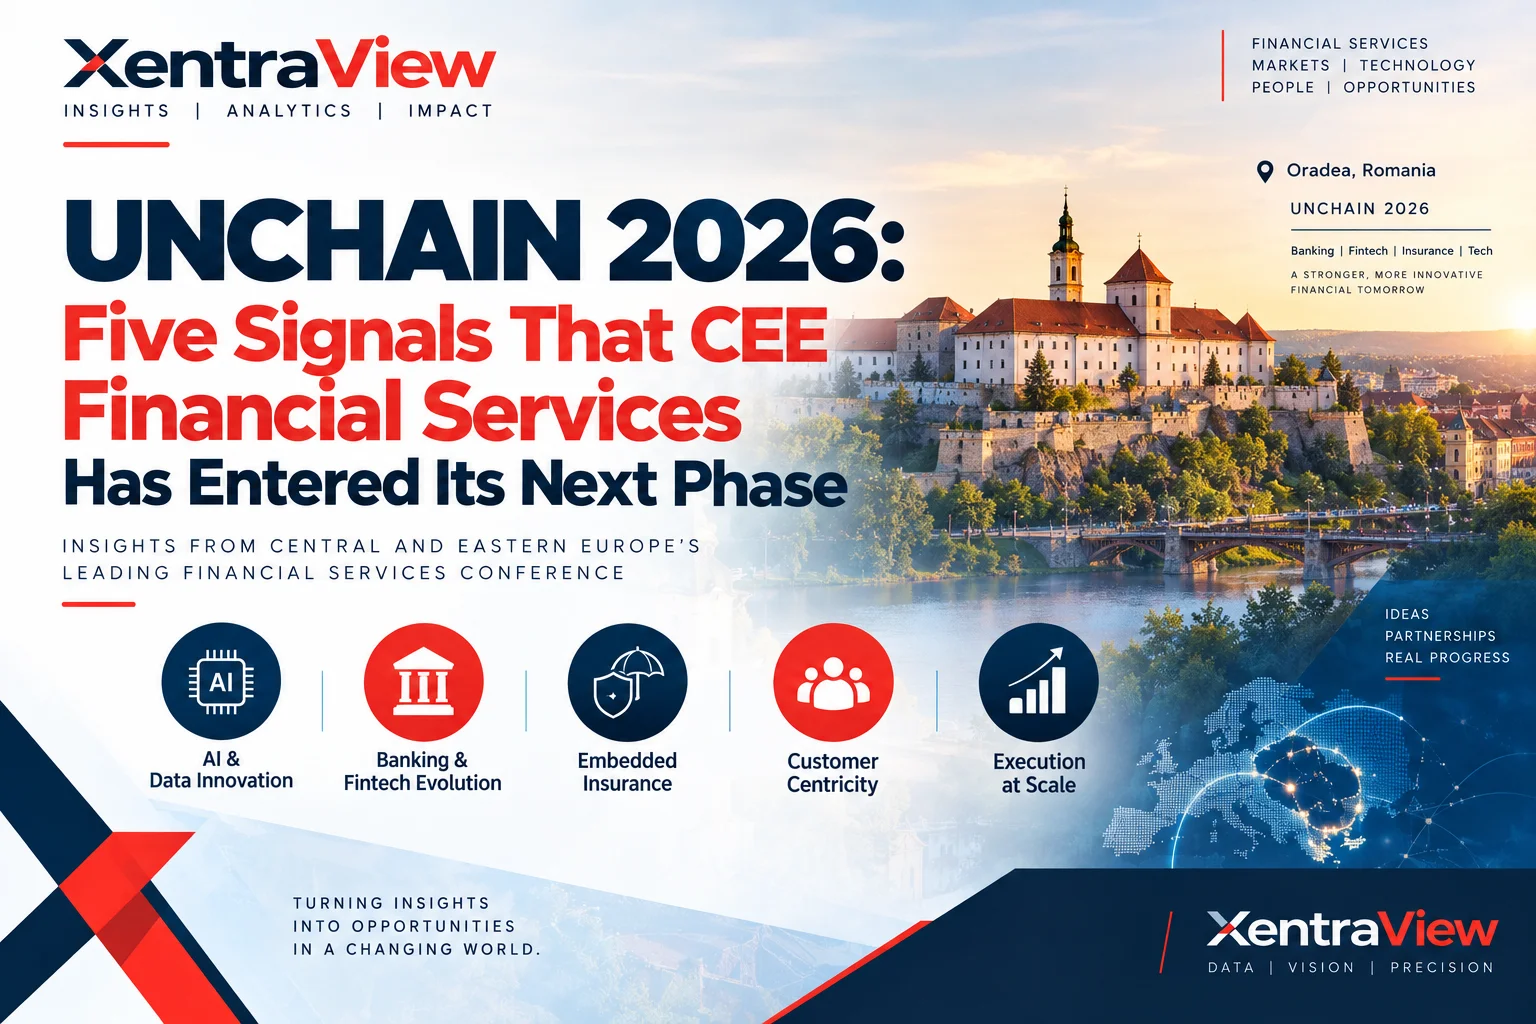
For most of the last thirty years, the story coming out of Central and Eastern Europe’s financial sector was fairly predictable: watch what mature Western markets were doing, then adopt it, a few years behind, at lower cost. UNCHAIN 2026, held inside a genuinely striking historic fortress in western Romania and drawing more than a thousand leaders from banking, fintech, insurance, and tech, told a different story this time around. Nobody was talking about catching up anymore. The conversation had moved on to execution, scale, and who actually owns what gets built.
Institutions across the region are increasingly building and investing on their own terms now, and the edge they’re working from isn’t really about being cheaper anymore. It’s a mix of strong technical talent, real digital maturity, and the kind of operational agility that’s harder to copy than a price point. Here’s what stood out most from the week and why it matters well beyond the region itself.
Insurance Is Quietly Becoming Something You Receive, Not Something You Buy
Insurance is slipping into the background of other purchases rather than standing on its own. Book a flight, take out a consumer loan, buy a phone, check out on an e-commerce site, increasingly there’s a policy attached before you’ve even thought to ask for one.
The topic that generated the most genuine curiosity in the room was parametric insurance. Instead of the usual claims process, adjuster visit, and reimbursement wait, a parametric policy just pays out automatically once a defined trigger happens. No claim to file, no assessment to wait on, nothing but the transaction itself. It’s easy to see why that appeals to anyone who’s ever sat on hold with an insurer: it’s fast, it’s simple, and it plugs into other products through an API without much friction at all.
Market forecasts vary depending on who’s doing the counting, but the direction is consistent. XentraView points to strong growth ahead for embedded insurance across Europe, and Strategy&, PwC’s consulting arm, expects it to become a genuinely major distribution channel by 2030. The real question at this point isn’t whether embedded insurance scales. It’s who ends up owning the customer once it does.
That question split the room a little. If insurance keeps dissolving into whatever product it’s attached to, does the carrier keep the relationship, does the broker, or does it belong to whoever built the platform doing the embedding? A long-established Greek composite insurer wasn’t buying the techno-optimism entirely, arguing that trust still wins in the end, that the claims experience is really the product, and that solid underwriting, partnerships, and local knowledge still decide who customers stick with. A newer, fully digital carrier pushed back on that, conceding that brokers still matter for genuinely complex risk but insisting that the digital experience itself is now what decides who holds the relationship.
Right now the market looks headed toward some hybrid of both. But the digital experience keeps creeping further into that decision, and it’s hard to see that trend reversing.
AI’s Real Problem Isn’t the AI
If there was one message that came up in nearly every banking session, it was this: the model isn’t the bottleneck anymore.
Financial institutions aren’t stuck because generative AI can’t do what’s asked of it. They’re stuck because their data is scattered, inconsistent, and badly connected to the workflows people actually use day to day. Layer on decades of legacy core banking systems, often bolted onto one another rather than designed together, and you end up with data locked in silos that simply isn’t accessible in real time even when the will to use it is there.
What surprised a few people in the room was how badly underestimated the actual effort is, extracting, cleaning, and reconciling data out of old platforms turns out to eat far more time than teams plan for, and that’s usually what slows execution down rather than any shortcoming in the model itself. Most enterprise generative AI pilots never produce measurable bottom-line results, and the bankers at UNCHAIN mostly attributed that to weak integration into everyday work rather than the underlying technology. Worth noting too: AI projects built alongside specialist partners seemed to have noticeably better track records than ones built purely in-house.
A few practical lessons kept surfacing. Clean and govern your data before you try to automate anything on top of it. Treat data like a business asset that the whole organisation is responsible for, not something IT quietly owns in a corner. And keep experimentation clearly separate from anything that’s actually going into production.
The institutions actually getting value out of AI aren’t necessarily running the most sophisticated models. They’re the ones that have figured out how to fold AI into the decisions people make every day. In environments this weighed down by legacy systems, execution beats technology every time.
Banks and Fintechs Are Starting to Look More Alike
One of the more surprising undercurrents at the conference was just how tired the old “banks can’t innovate” line has gotten.
One major regional bank talked about running hundreds of in-house engineers organised into product teams, sounding a lot more like a tech company describing its org chart than a traditional bank. Several people in the room mentioned, almost in passing, that established banks have become a genuinely attractive place for engineering and AI talent to land now, offering hard problems, real datasets at scale, and a level of stability that early-stage startups just can’t match.
The industry’s sense of who the real threat is has shifted too. It’s not really the scrappy early-stage startup anymore. It’s the digital-first challenger that’s already gotten to scale and is now competing on the same footing as everyone else.
For CEE institutions specifically, a few advantages kept coming up: strong engineering talent, cost-to-capability economics that are hard to beat elsewhere in Europe, and deep technical depth spanning both software and data. The question isn’t whether these institutions can build anymore. It’s whether they can govern, prioritize, and scale what they’ve already started building.
Hyper-Personalisation Is Moving From Nice-to-Have to Priority
However the conversation started, whether infrastructure, compliance, or AI, it kept circling back to the customer eventually.
The goal is simple to state: move away from static product menus and toward guidance that shows up at the right moment, through the right channel, for the right person. Getting there is a lot less simple.
Try to personalise at scale and every weakness in your data setup shows up almost immediately. Fragmented customer records, inconsistent information across systems, and disconnected platforms, these stop being background annoyances and become the actual barrier the moment personalisation becomes the goal.
There was a real tension raised too: where does personalisation stop and intrusion begin? Nobody had a clean answer, and it seemed to depend a lot on how much trust a customer already has in the institution and on a regulatory environment that’s still working to catch up with what the technology can actually do. Get hyper-personalization right, and it becomes a genuine edge. Get it wrong and it undermines the exact trust the whole approach depends on. It isn’t really a separate initiative sitting alongside data and governance work. It’s what you get once that work is actually done properly.
Europe’s Standing in the AI Race Isn’t Settled
Underneath all the optimism sat a more sober conversation about whether Europe can stay competitive in AI at a global level.
The worries were familiar ones, limited homegrown cloud infrastructure, heavy reliance on foundation models built elsewhere, and shrinking visibility into the technology layers that matter most. A keynote from a former Polish prime minister and central bank governor sharpened that concern further, arguing that Europe tends to regulate new technology before it’s built the conditions that let innovation actually happen in the first place.
There was a more hopeful note too. History does show that technological shifts can let regions leapfrog ahead of incumbents rather than just follow them. But leapfrogging takes more than ambition, it takes disciplined execution, real investment, and a willingness to actually ship things rather than keep experimenting indefinitely. That challenge sits with institutions just as much as it sits with policymakers.
The Bottom Line
What stood out most from UNCHAIN 2026 was how clearly the region has moved past the adoption phase of digital transformation. The raw ingredients, talent, entrepreneurial drive, strong institutions, and growing technical capability, are already there. What’s left is execution.
Embedded insurance is heading into the mainstream, and competition is shifting from who distributes the product to who owns the customer relationship. AI success is going to come down to data quality, integration, and operational discipline far more than model sophistication. Banks are proving they can build and innovate at a real scale, drawing on the deep engineering talent the region has cultivated. Hyper-personalisation is emerging as the next real battleground, but only for organisations that can earn and then hold onto trust. And Europe’s long-term footing in all of this depends on whether it can balance innovation, regulation, and genuine technological independence, rather than defaulting to one at the expense of the others.
CEE financial services doesn’t look like it’s catching up to anyone anymore. It looks like it’s writing its own playbook, and the rest of the industry would do well to pay attention to how that plays out.
